Invoices, payments and taxes for car repair workshops and mechanics

FIZ issues the invoice for every repair, with labour and parts, takes card payments on your phone, gathers your expenses from e‑Fatura, such as parts and oil, and prepares your Seg. Social and IVA declarations and submits them with one click from you.

How do you work?
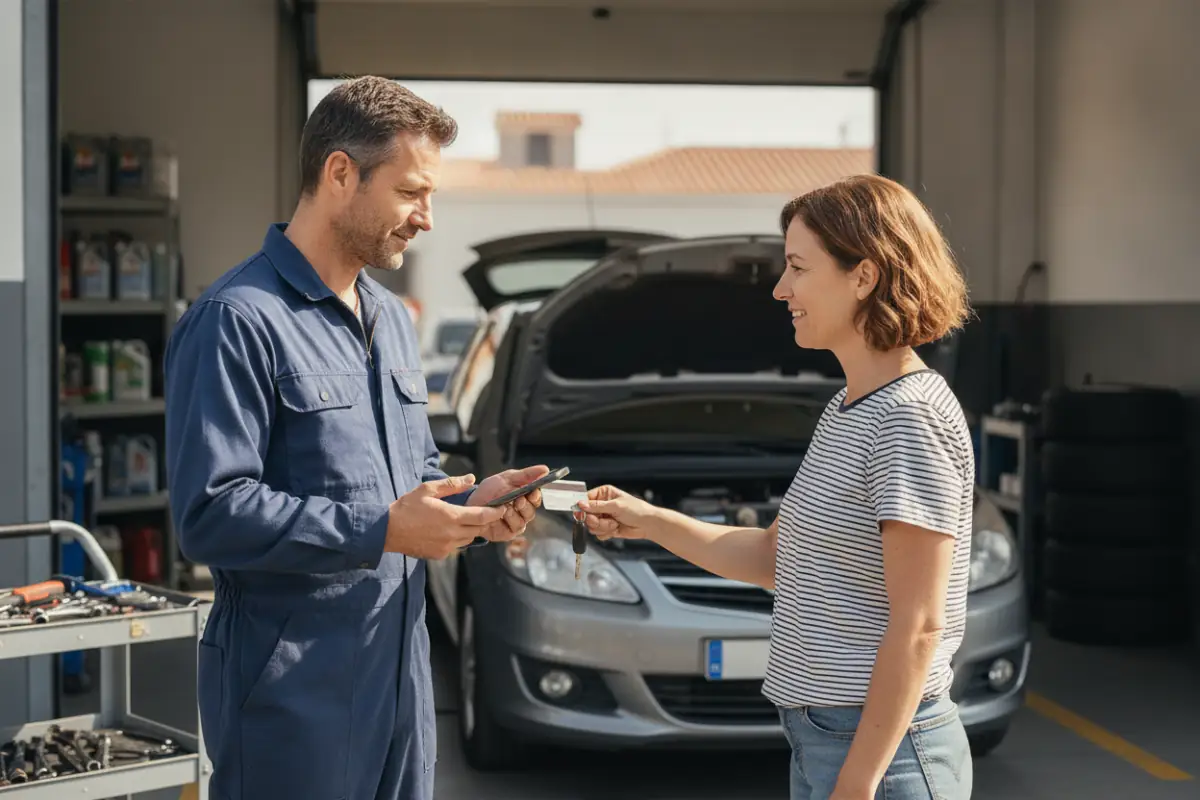
A mechanic holds his phone while a customer pays contactless by card, next to a car with its bonnet open, in a small workshop in Lisbon.
  • 4.9
  • 15,000 clients
  • AT-certified no. 3041
Try free

Every day: the repair is paid and the invoice goes out at once

When you hand back the car, issue the repair invoice in FIZ, with labour and parts. The customer pays contactless on your phone or scans a QR code, and FIZ reports the invoice to the AT.

It works the same for a repair at the client’s place, with no terminal to buy or rent. Each payment has a fee, which depends on the plan.

Accept paymentsCertified invoicing

Contactless

The customer holds a contactless card, or a phone with Apple Pay or Google Pay, near your phone.

By QR code

Show the QR code to your customer. They scan it and complete the payment on their own phone.
Expenses: FIZ imports your purchase invoices

When you buy parts, oil or tools with your NIF, the supplier’s invoice lands in the AT’s e‑Fatura. FIZ fetches it by itself and suggests whether the expense is business, personal or mixed.

Expenses and tax deductions
Brake pads and discs

Autopeças Lusitânia, Lda. · Portuguese supplier invoice

Amount excluding IVA
210.00 €
IVA (23%)
48.30 €
Payable to the supplier
258.30 €

If you charge IVA, this IVA is deducted from the IVA on your sales. With the IVA exemption, it stays a cost.

Example with sample data

At the end of the quarter: the declarations are ready

FIZ calculates your Seg. Social contribution from your invoices, prepares the quarterly declaration and submits it with one click from you.

If you charge IVA, FIZ does the same with the periodic IVA declaration.

Segurança Social for the self-employedIVA declaration for the self-employed
Seg. Social quarterly declaration

July to September (3 months)

Repairs (3 months): 70% of 6,000 €
4,200 €
Parts over the counter (3 months): 20% of 1,500 €
300 €
Monthly base: one third
1,500 €
Monthly contribution: 25.2%
378 €
Periodic IVA declaration

July to September (3 months)

IVA on sales
1,725.00 €
Deductible IVA
−690.00 €
IVA due
1,035.00 €
Example with sample data: an empresário em nome individual who declared only commercial or industrial activity to Seg. Social, rate 25.2%.

Start using FIZ today.

Don’t wait for the quarter or another software subscription to end: FIZ imports invoices, customers and products from Portal das Finanças, SAF‑T, Excel or CSV and includes the invoices in your declarations.

A woman working on a laptop at a table at home
From Portal das Finanças to FIZ

A free month for you and one for your invitee

Share your invitation link with anyone who does not use FIZ yet. When your invitee signs up and issues their first invoice in FIZ, you each get a free month on a paid plan.

Your free months add up with no limit and do not expire.

To invite someone, all you need is a FIZ account connected to AT.

Two colleagues sharing an invitation on a phone
You1 free monthfor each invitee who issues their first invoice
Your invitee1 free monthwhen they issue their first invoice

Choose a plan for your business

Frequently asked questions about workshops and mechanics

Which CAE does a car repair workshop use?

In CAE-Rev.4, in force since 2025, it is 95310, «Reparação e manutenção de veículos automóveis», also for a mechanic who repairs at the client’s place. In CAE-Rev.3, the code was 45200, «Manutenção e reparação de veículos automóveis».

If you also sell parts over the counter, you can add 47820, «Comércio a retalho de peças e acessórios para veículos automóveis», as a secondary activity.

Decree-Law 9/2025 (CAE-Rev.4) (Opens in a new window)Decree-Law 381/2007 (CAE-Rev.3) (Opens in a new window)

Does a self-employed mechanic on recibos verdes charge IVA?

Yes, unless exempt: 23% on repairs and parts, on the mainland. If you invoiced up to 15,000 € in the previous year, or expect no more than that in the year you start, you can invoice without IVA; then the IVA on the parts and tools you buy stays a cost.

If you pass 18,750 € in the current year, you lose the exemption and charge IVA from that moment.

IVA Code, art. 18 (Opens in a new window)IVA Code, art. 53 (Opens in a new window)art. 58 (Opens in a new window)

Which IRS coefficient applies to a mechanic?

In the simplified regime, repairs have the coefficient 0.35: 35% of what you invoice counts as income. With 24,000 € in repairs, IRS is worked out on 8,400 €. Mechanics are not in the IRS activity table, so the 0.75 coefficient does not apply. Parts sold over the counter, without a repair, have the coefficient 0.15.

To avoid paying more IRS than you need to, business expenses need to reach 15% of what you invoice for services. Business invoices on e‑Fatura, the rent for your premises and the salaries you pay count, plus a fixed amount the law already allows for, or your Seg. Social contributions if they are higher. If the total is below 15%, the difference is added to your taxable income. FIZ shows how much is left to reach 15%.

In the year you open your activity, the services coefficient is reduced by 50%, and the next year by 25%, if in those years you receive no salary or pension and have not closed an activity in the previous five years.

IRS Code, art. 28 (Opens in a new window)art. 31 (Opens in a new window)IRS activity table (Opens in a new window)

Does a workshop invoice have to list parts and labour separately?

Yes: the invoice shows each part and the service provided, with the quantity and the price, as the IVA Code requires. In FIZ, each invoice line is a product or a service, with its own IVA rate.

A simplified invoice can be used for repairs of up to 100 € and for sales of parts to private customers of up to 1,000 €; with the IVA exemption, with no limit.

IVA Code, art. 29 (Opens in a new window)art. 36 (Opens in a new window)art. 40 (Opens in a new window)

How is Seg. Social worked out for a self-employed mechanic?

Under the simplified regime, Seg. Social counts 70% of repairs and 20% of parts sold over the counter, without IVA, and the monthly contribution base is a third of that amount for the quarter. The rate is 21.4%, or 25.2% if you declare to Seg. Social that you are an empresário em nome individual with only commercial or industrial activity. Anyone working as self-employed for the first time pays no contributions for 12 months.

FIZ calculates the contribution from your invoices, prepares the quarterly declaration and submits it with one click from you.

Contributions Code, art. 162 (Opens in a new window)art. 168 (Opens in a new window)

Can I open a workshop as an empresário em nome individual?

Yes. You open the activity with the Finanças under CAE 95310 and invoice with your own NIF, without setting up a company. With turnover up to 200,000 € in the previous year, you stay in the IRS simplified regime. The Seg. Social contribution is 21.4%, or 25.2% if you declare that you are an empresário em nome individual with only commercial or industrial activity.

IRS Code, art. 28 (Opens in a new window)art. 31 (Opens in a new window)IRS activity table (Opens in a new window)Contributions Code, art. 162 (Opens in a new window)art. 168 (Opens in a new window)

What changes when the workshop is a company?

The CAE, IVA and invoice rules stay the same. The company pays IRC on profit and keeps full accounting (contabilidade organizada) with a certified accountant.

IRC is filed in the Modelo 22 by the end of May. Under the simplified regime, with turnover up to 200,000 € and the other legal conditions, it is worked out on 10% of repairs and 4% of parts sold without a repair.

In FIZ, the company’s certified accountant confirms the IVA declaration with one click and FIZ submits it to the AT.

IRC Code, art. 86‑A (Opens in a new window)art. 86‑B (Opens in a new window)IRC Code, art. 123 (Opens in a new window)OCC Statute, art. 10 (Opens in a new window)

Checked on 15 October 2026

IRS declaration

Other industries

Sector catalogue