Invoices, payments and taxes for cleaning services

FIZ issues the invoice for every cleaning job and the scheduled invoices of a monthly contract, takes card payments on your phone, gathers your expenses from e‑Fatura and prepares your Seg. Social and IVA declarations and submits them with one click from you.

How do you work?
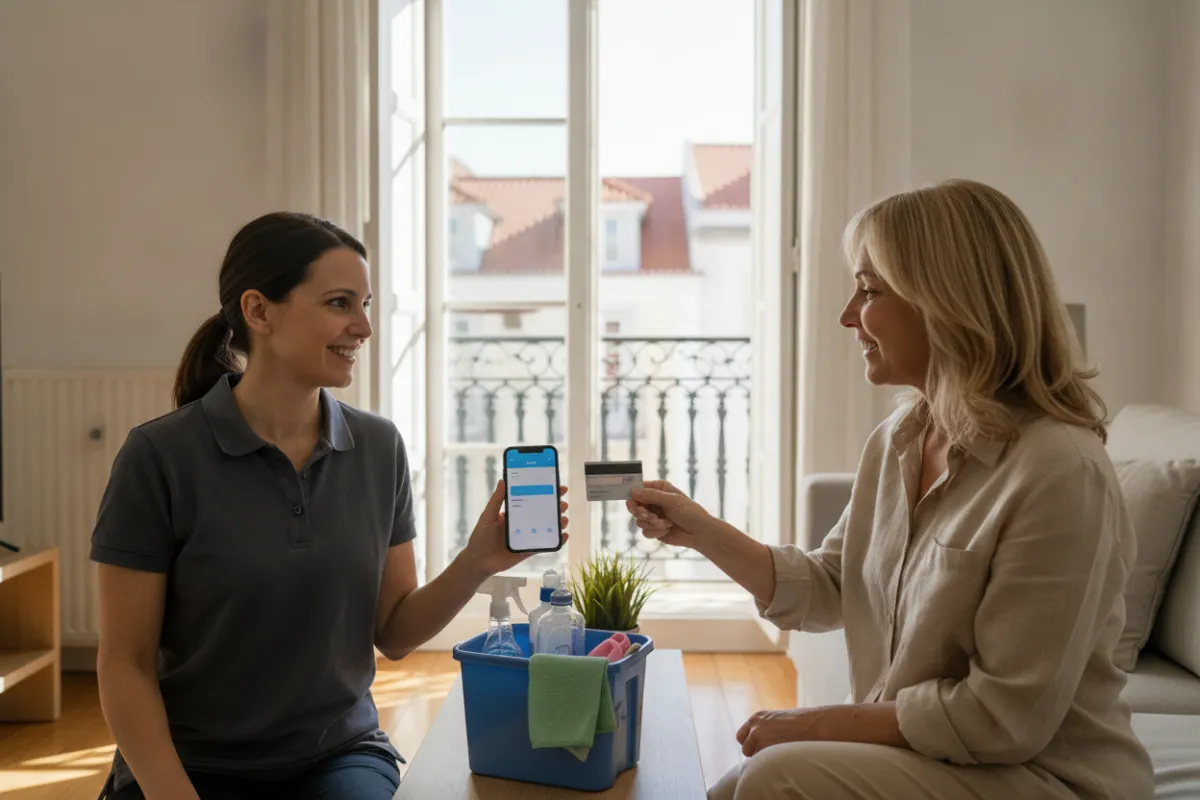
A cleaner shows her phone and the client pays contactless by card, in a bright living room in Lisbon, with a caddy of cleaning products on the table.
  • 4.9
  • 15,000 clients
  • AT-certified no. 3041
Try free

Every day: the cleaning is paid and the invoice goes out at once

When the cleaning is done, issue the invoice in FIZ. The client pays contactless on your phone or scans a QR code, and FIZ reports the invoice to the AT. Each payment has a fee, which depends on the plan.

On a monthly contract, such as one for an office or the common areas of a building, FIZ issues the scheduled invoices on the day you choose and reports them to the AT.

Accept paymentsCertified invoicing

Contactless

The customer holds a contactless card, or a phone with Apple Pay or Google Pay, near your phone.

By QR code

Show the QR code to your customer. They scan it and complete the payment on their own phone.
Expenses: FIZ imports your purchase invoices

When you buy cleaning products, a vacuum cleaner or fuel with your NIF, the supplier’s invoice lands in the AT’s e‑Fatura. FIZ fetches it by itself and suggests whether the expense is business, personal or mixed.

Expenses and tax deductions
Cleaning products

Higiene do Tejo, Lda. · Portuguese supplier invoice

Amount excluding IVA
150.00 €
IVA (23%)
34.50 €
Payable to the supplier
184.50 €

If you charge IVA, this IVA is deducted from the IVA on your sales. With the IVA exemption, it stays a cost.

Example with sample data

At the end of the quarter: the declarations are ready

FIZ calculates your Seg. Social contribution from your invoices, prepares the quarterly declaration and submits it with one click from you.

If you charge IVA, FIZ does the same with the periodic IVA declaration.

Segurança Social for the self-employedIVA declaration for the self-employed
Seg. Social quarterly declaration

July to September (3 months)

Services (3 months): 70% of 4,500 €
3,150 €
Monthly base: one third
1,050 €
Monthly contribution: 21.4%
225 €
Periodic IVA declaration

July to September (3 months)

IVA on sales
1,035.00 €
Deductible IVA
−69.00 €
IVA due
966.00 €
Example with sample data

Start using FIZ today.

Don’t wait for the quarter or another software subscription to end: FIZ imports invoices, customers and products from Portal das Finanças, SAF‑T, Excel or CSV and includes the invoices in your declarations.

A woman working on a laptop at a table at home
From Portal das Finanças to FIZ

A free month for you and one for your invitee

Share your invitation link with anyone who does not use FIZ yet. When your invitee signs up and issues their first invoice in FIZ, you each get a free month on a paid plan.

Your free months add up with no limit and do not expire.

To invite someone, all you need is a FIZ account connected to AT.

Two colleagues sharing an invitation on a phone
You1 free monthfor each invitee who issues their first invoice
Your invitee1 free monthwhen they issue their first invoice

Choose a plan for your business

Frequently asked questions about cleaning services

Which CAE code is used for cleaning?

In CAE-Rev.4, in force since 2025, cleaning houses, flats, offices and the common areas of buildings uses 81210, «Limpeza geral de edifícios». Specialised cleaning, such as windows, has 81220. In CAE-Rev.3, these two codes were the same.

Other cleaning now has 81232, which was 81292 in CAE-Rev.3, and disinfection and pest control 81231, formerly 81291.

Decree-Law 9/2025 (CAE-Rev.4) (Opens in a new window)Decree-Law 381/2007 (CAE-Rev.3) (Opens in a new window)

Does a self-employed cleaner (recibos verdes) charge IVA?

Yes, unless exempt: 23% on the mainland. Anyone who invoiced up to 15,000 € in the previous year, or expects that much in the year they start, can invoice without IVA; then the IVA on the products you buy stays a cost.

If you pass 18,750 € in the current year, you lose the exemption and charge IVA from that moment.

IVA Code, art. 18 (Opens in a new window)Lista I, verba 2.27 (Opens in a new window)IVA Code, art. 53 (Opens in a new window)art. 58 (Opens in a new window)

Which IVA rate applies to cleaning services?

23% on the mainland, for homes, offices and buildings. The 6% rate for renovation, repair or upkeep work on a home expressly leaves cleaning out. In the Azores and Madeira, each region’s normal rate applies.

IVA Code, art. 18 (Opens in a new window)Lista I, verba 2.27 (Opens in a new window)

What is the difference between domestic service and recibos verdes?

In domestic service, the person works regularly for a household, under its instructions, and earns a salary: the household is the employer, with an employment contract and Seg. Social contributions.

On recibos verdes, the person works on their own account, for one client or several, and issues an invoice for each service or each month of a contract. They pay IRS and Seg. Social as a self-employed worker.

A simplified invoice works for jobs up to 100 €; with the IVA exemption, with no limit.

Decree-Law 235/92, art. 2 (Opens in a new window)Contributions Code, art. 116 (Opens in a new window)IVA Code, art. 29 (Opens in a new window)art. 7 (Opens in a new window)art. 40 (Opens in a new window)

Which IRS coefficient applies to cleaning?

In the simplified regime, cleaning services have the coefficient 0.35: 35% of what you invoice counts as income. With 18,000 € in services, IRS is worked out on 6,300 €. Cleaning is not in the IRS activity table, so the 0.75 coefficient does not apply.

To avoid paying more IRS than you need to, business expenses need to reach 15% of what you invoice for services. Business invoices on e‑Fatura, the rent for your premises and the salaries you pay count, plus a fixed amount the law already allows for, or your Seg. Social contributions if they are higher. If the total is below 15%, the difference is added to your taxable income. FIZ shows how much is left to reach 15%.

In the year you open your activity, the services coefficient is reduced by 50%, and the next year by 25%, if in those years you receive no salary or pension and have not closed an activity in the previous five years.

IRS Code, art. 28 (Opens in a new window)art. 31 (Opens in a new window)IRS activity table (Opens in a new window)

How is Seg. Social worked out for self-employed cleaners?

Under the simplified regime, Seg. Social counts 70% of services, without IVA, and the monthly contribution base is a third of that quarterly amount. The rate is 21.4%, or 25.2% if you declare to Seg. Social that you are an empresário em nome individual with only commercial or industrial activity. If you work as self-employed for the first time, you pay no contributions for 12 months.

FIZ calculates the contribution from your invoices, prepares the quarterly declaration and submits it with one click from you.

Contributions Code, art. 162 (Opens in a new window)art. 168 (Opens in a new window)

Which IVA applies to cleaning a short-term rental (alojamento local)?

The cleaning invoice to the host carries IVA at 23%, unless the cleaner is exempt. The 6% rate is the one for the stay the host invoices to the guest, with the cleaning fee charged with it.

If the host charges IVA on stays, they deduct the 23% on the cleaning invoice in their periodic declaration.

IVA Code, art. 18 (Opens in a new window)Lista I, verba 2.27 (Opens in a new window)

What changes when you have a cleaning company?

The CAE, IVA and invoice rules stay the same. The company pays IRC on profit and keeps full accounting (contabilidade organizada) with a certified accountant.

IRC is filed in the Modelo 22 by the end of May. Under the simplified regime, with turnover up to 200,000 € and the other legal conditions, it is worked out on 10% of services.

In FIZ, the company’s certified accountant confirms the IVA declaration with one click and FIZ submits it to the AT.

IRC Code, art. 86‑A (Opens in a new window)art. 86‑B (Opens in a new window)IRC Code, art. 123 (Opens in a new window)OCC Statute, art. 10 (Opens in a new window)

Checked on 15 October 2026

IRS declaration

Other industries

Sector catalogue